
The Federal Government has introduced a new regime for calculating interest on late payment of taxes, reducing the additional interest charged on naira-denominated tax liabilities from five percentage points to one percentage point above the Central Bank of Nigeria’s (CBN) Monetary Policy Rate (MPR).
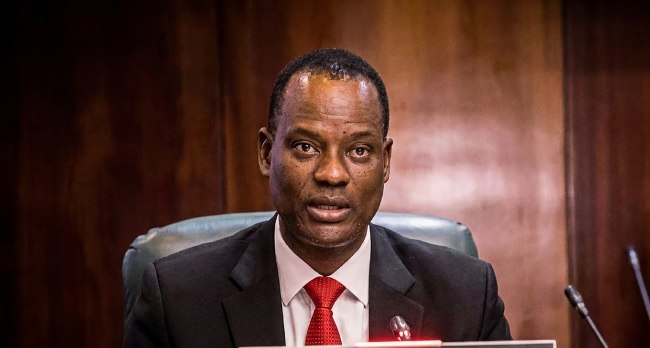
The measure is contained in the Nigeria Tax Administration (Interest on Late Payment of Tax) Order, 2026, issued by the Minister of Finance and Coordinating Minister of the Economy, Taiwo Oyedele, under Section 65 of the Nigeria Tax Administration Act, 2025.
The new regime will take effect from October 1, 2026.
How the New Tax Interest Will Work
Under the new framework, interest on taxes payable in naira will be calculated at the CBN’s MPR plus one percentage point.
However, the applicable rate cannot fall below the yield on 364-day Treasury Bills, which the government says reflects its funding cost when tax payments are delayed.
For tax liabilities payable in foreign currencies, the applicable interest rate will be based on the Secured Overnight Financing Rate (SOFR) plus six percentage points. If SOFR is discontinued, its officially designated successor benchmark will apply.
The change replaces the previous five-percentage-point spread and links late-payment interest more closely to prevailing market benchmarks.
Interest Rate to Be Published Monthly
The new order provides for a single applicable interest rate for each calendar month.
The Nigeria Revenue Service (NRS) is required to publish the applicable rate on its website by the third business day of each month. The rate will be determined using the relevant benchmark on the last business day of the preceding month.
Interest will be calculated as simple interest on a daily basis, beginning from the date the tax becomes due until the outstanding liability is paid.
The framework applies to self-assessment taxpayers as well as tax obligations administered by the NRS, state internal revenue services and the Federal Capital Territory Internal Revenue Service.
10% Late-Payment Penalty Remains
The reduction in the interest spread does not eliminate the separate statutory penalty for late payment.
The Federal Government said the 10 per cent penalty provided under Section 65 of the Nigeria Tax Administration Act remains in force.
Tax authorities also retain powers under Section 66 to waive applicable interest or penalties where a taxpayer demonstrates good cause.
This means taxpayers who fail to meet their obligations on time could still face both the statutory penalty and the applicable market-linked interest, subject to the provisions of the law and any approved waiver.
New Rules Also Cover Outstanding Tax Liabilities
The government said the new rates will apply to interest arising from October 1, 2026, including interest relating to tax liabilities that became due before that date.
However, interest that had already accrued before October 1 will remain subject to the rules applicable when it arose, where those rules specifically provide for such treatment.
The 2026 Order also supersedes the 2017 notice on interest on unpaid taxes and other earlier notices dealing with the same issue.
Oyedele Explains Government’s Position
Oyedele said the new framework was designed to ensure that the financial cost of delaying tax payments reflects prevailing market conditions.
He said late payment could require government to borrow to compensate for revenue that should already have been received.
The minister also said the monthly publication of rates would give taxpayers greater certainty about the cost of outstanding tax liabilities.
According to him, the system is intended to ensure that delaying tax payments does not become a cheaper source of financing than borrowing from the market.
The Federal Government has consequently advised taxpayers to file their returns and settle their tax obligations within the prescribed deadlines.
Taxpayers with outstanding liabilities have also been encouraged to settle them promptly or engage the relevant tax authority regarding their obligations.